Key Takeaways for Homeowners
- •Most Texas policies cover resulting water damage from sudden, accidental pipe bursts.
- •The plumber's direct pipe repair is typically the homeowner's out-of-pocket responsibility.
- •Tear-out coverage often pays for jackhammering or tunneling to access sub-slab pipes.
- •Gradual leaks ongoing for months are frequently excluded under wear-and-tear clauses.
Direct Answer: What Texas Insurance Policies Typically Cover
In Texas, standard homeowners insurance policies (such as HO-B and comprehensive HO-3 forms) generally cover resulting water damage to flooring, drywall, cabinetry, and personal belongings caused by sudden and accidental plumbing discharge, as well as the 'tear-out' cost required to access the leaking pipe through a concrete slab or wall. However, the direct plumbing repair—the actual cost for the plumber to solder or replace the split pipe section—is typically excluded as routine plumbing maintenance.
Understanding this division between 'access and resulting damage' versus 'pipe repair' is essential when filing a claim in Duncanville, Cedar Hill, or DeSoto.
The Critical Distinction: Repair vs. Access (Tear-Out)
When a slab leak occurs beneath a concrete foundation, total remediation costs are divided into three categories:
1. Direct Plumbing Pipe Repair: Cutting out the pinhole copper leak and brazing in a replacement fitting. Typically costs $400 to $900 and is usually paid out-of-pocket by the homeowner.
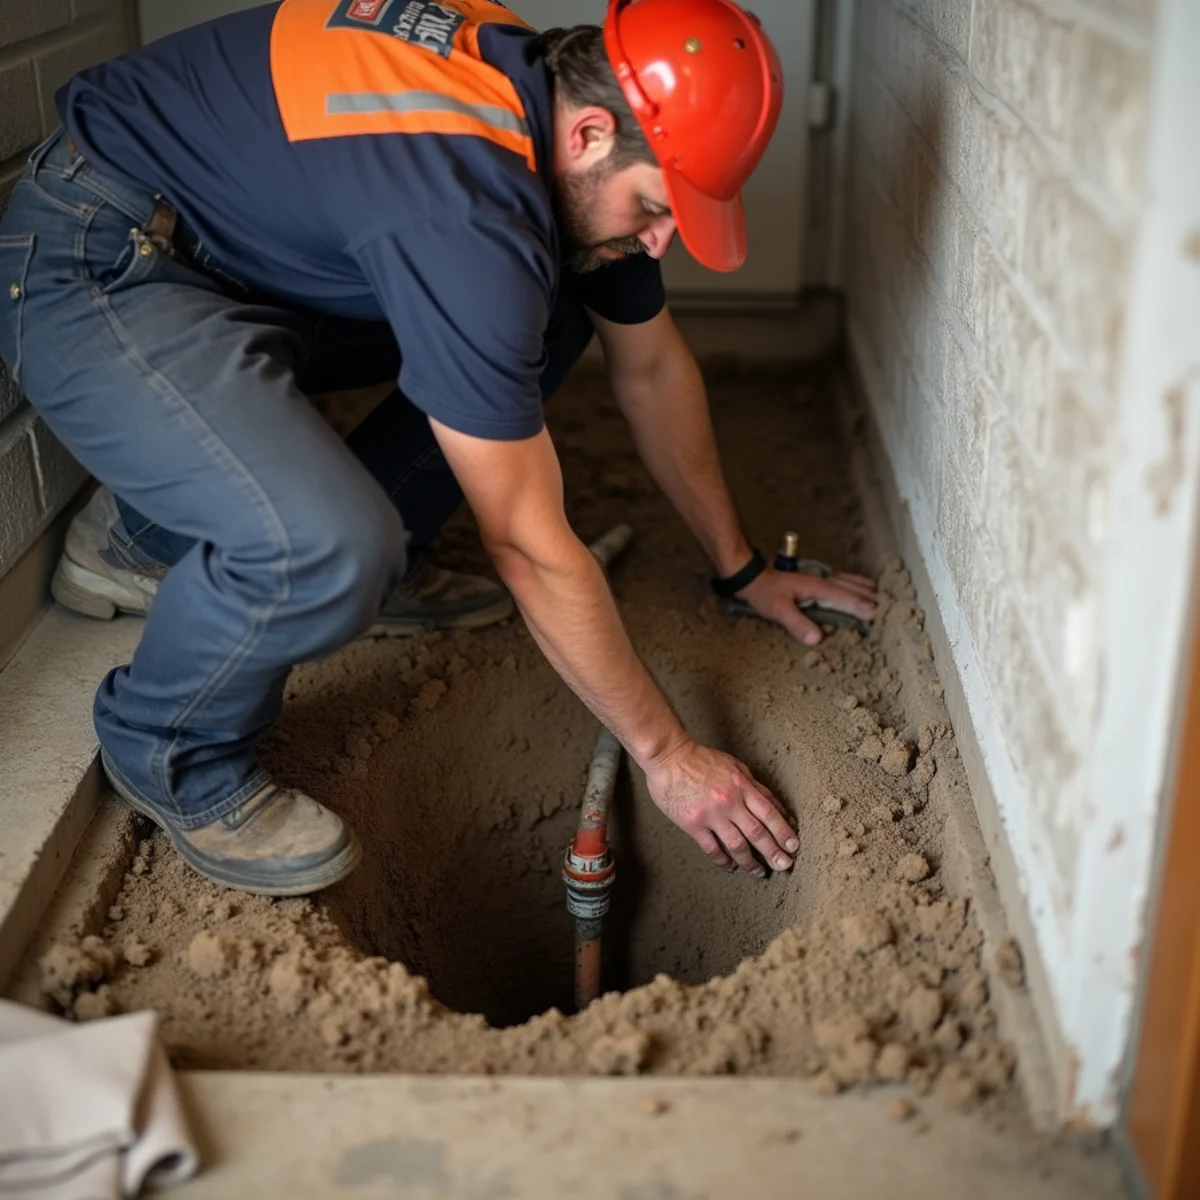
2. Access / Tear-Out: The labor and equipment required to jackhammer through finished flooring and reinforced slab concrete, or tunnel 15 feet beneath the foundation perimeter. This often costs $2,000 to $5,000+ and is widely covered under standard Texas policy tear-out provisions.
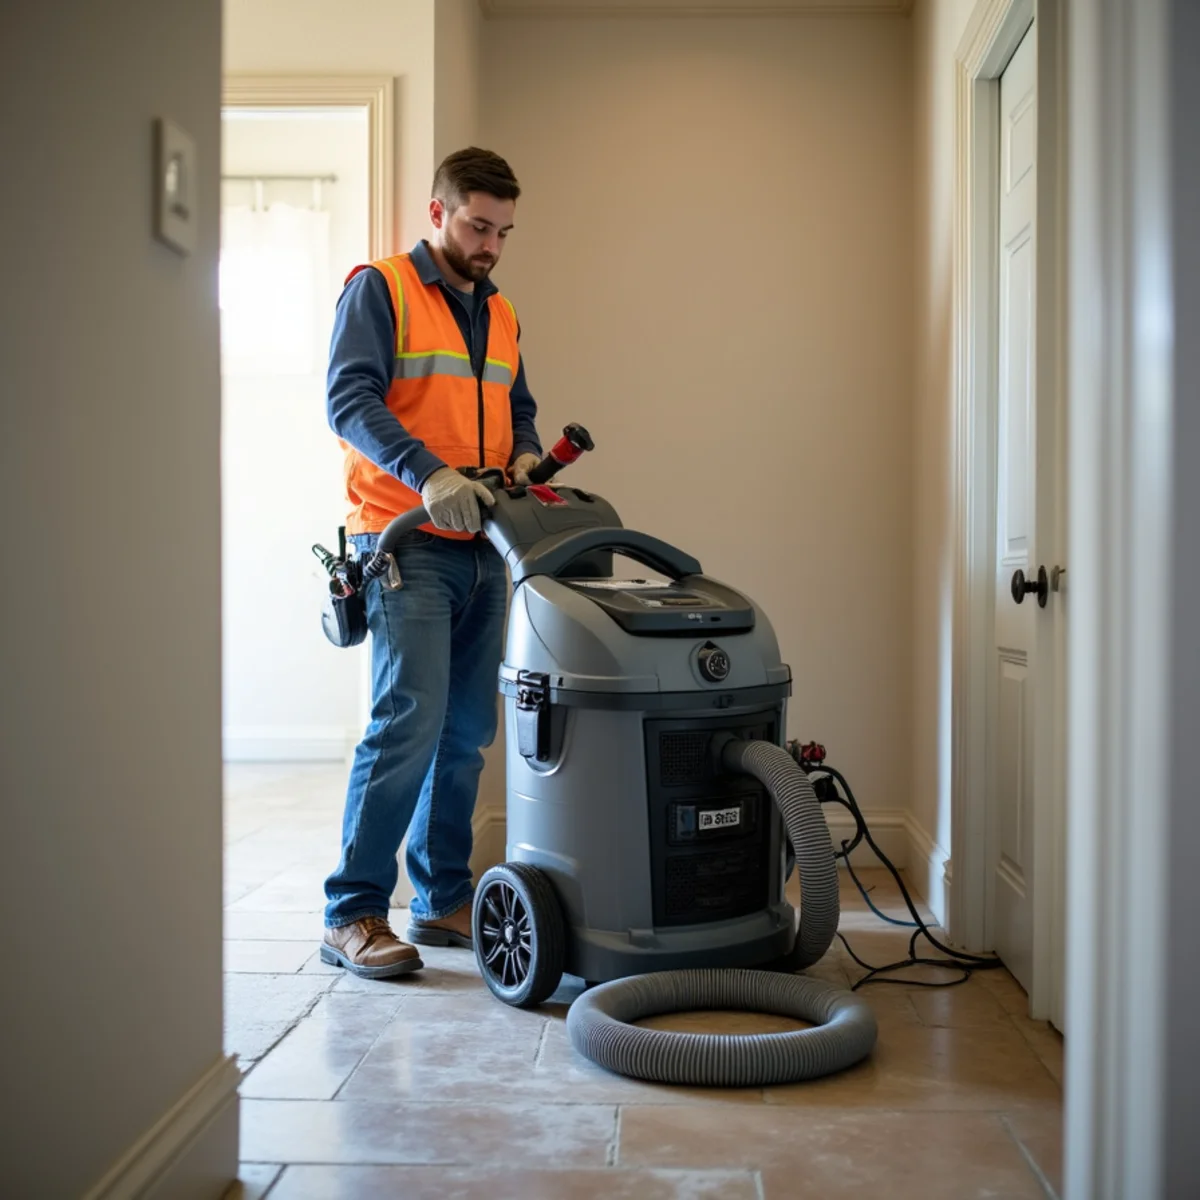
3. Resulting Water Damage Restoration: Drying out saturated subfloors, replacing baseboards, remediating mold, and installing new flooring. Covered under standard accidental discharge clauses.
Sudden & Accidental vs. Gradual Leaks
Insurance adjusters scrutinize water damage claims for evidence of duration. If a burst pipe ruptures overnight during a winter freeze, it is unambiguously sudden and accidental. However, if a sub-slab leak has been weeping for six months—creating visible rot, rust, and widespread fungal decay—insurers may attempt to deny coverage under 'continuous or repeated seepage' exclusions.
Reporting leaks promptly the moment you notice water meter movement or floor warmth is vital to preserving your coverage rights.
Need Hands-On Emergency Assistance?
Speak directly with our local Duncanville dispatch desk at (858) 363-8298.
How Ten Mile Creek Plumbers Documents Claims for Adjusters
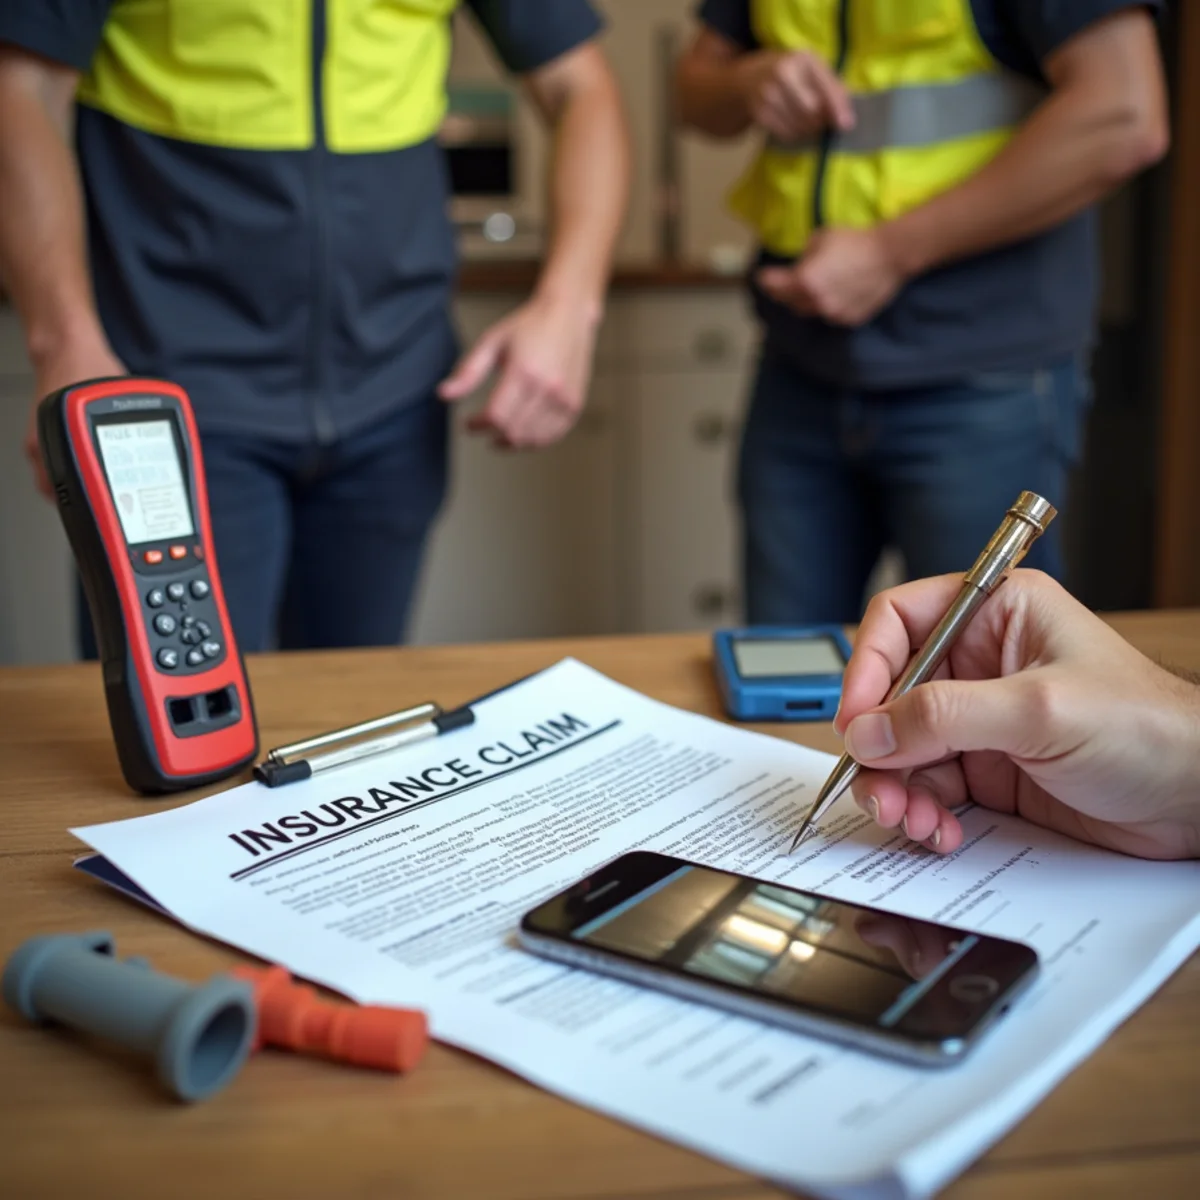
Our technicians assist homeowners by providing complete documentation packages required by major Texas insurance carriers (State Farm, Allstate, USAA, Farmers). We supply: itemized invoices separating access from plumbing repair, digital acoustic leak detection reports, thermal imaging photographs showing the exact leak perimeter, and photos of the failed fitting.
Texas Insurance Policy Coverage Matrix: Slab Leaks vs Pipe Bursts
| Loss Component | Standard HO-3 / HO-B Coverage | Typical Financial Allocation | Adjuster Inspection Criteria |
|---|---|---|---|
| Sub-Slab Tear-Out (Jackhammering/Tunneling) | Covered under access provisions | $2,200 – $6,500 paid by insurer | Requires invoice proof that leak could not be accessed otherwise |
| Physical Plumbing Pipe Solder/Reroute | Excluded (Homeowner responsibility) | $450 – $1,800 paid out-of-pocket | Separated on plumbing invoice as distinct repair line item |
| Emergency Water Extraction & Dehumidification | Covered under loss mitigation | $1,500 – $4,500 paid by insurer | Time-stamped psychrometric moisture logs and dryout logs |
| Finished Flooring, Drywall & Cabinet Restoration | Covered under dwelling property loss | $3,500 – $18,000+ paid by insurer | Proof of continuous flooring replacement and like-kind quality |
| Sub-Slab Sewer Lateral Collapse (Aging Drain) | Excluded unless utility rider endorsed | $4,000 – $12,000 paid out-of-pocket | Wear-and-tear / age deterioration exclusions applied |
How Line-Item Invoice Separation Protects Homeowners from Insurance Denials
In our decades navigating Dallas County plumbing insurance claims, the most common reason adjusters deny slab leak reimbursement is poorly formatted plumbing invoices. If an inexperienced contractor submits a single lump-sum invoice stating 'Slab Leak Repair: $4,800', the insurance adjuster will reflexively classify the entire amount as excluded plumbing maintenance. At Ten Mile Creek Plumbers, we furnish adjusters with forensic line-item invoicing: strictly separating the $450 direct pipe repair from the $3,800 required for foundation excavation, concrete coring, backfilling, and structural restoration. Under Texas Insurance Code, carriers must honor the access and tear-out portion when clearly demarcated by a licensed Master Plumber.
Frequently Asked Questions
Practical answers from our local plumbing repair team.
Many insurance adjusters approve overhead PEX reroutes because the cost of rerouting through an attic is frequently less expensive than paying for slab jackhammering, concrete remediation, and custom flooring replacement. Presenting a comparative estimate showing cost savings to your adjuster often secures full or partial coverage.
Related Services & Local Coverage
Explore our dedicated service options and neighboring dispatch areas:
Don't Let Plumbing Problems Escalate
Every plumber we send is licensed and insured in Texas. Upfront written price given before work starts.
Not Urgent? Send a Service Request
If your plumbing project can wait for scheduled daytime evaluation, submit your details below. We will coordinate with an independent licensed Texas plumber in Duncanville to confirm your appointment.
Do not wait for a form response if water is spreading or sewage is surfacing. For the fastest help, call immediately:
(858) 363-8298 (Answering 24/7)